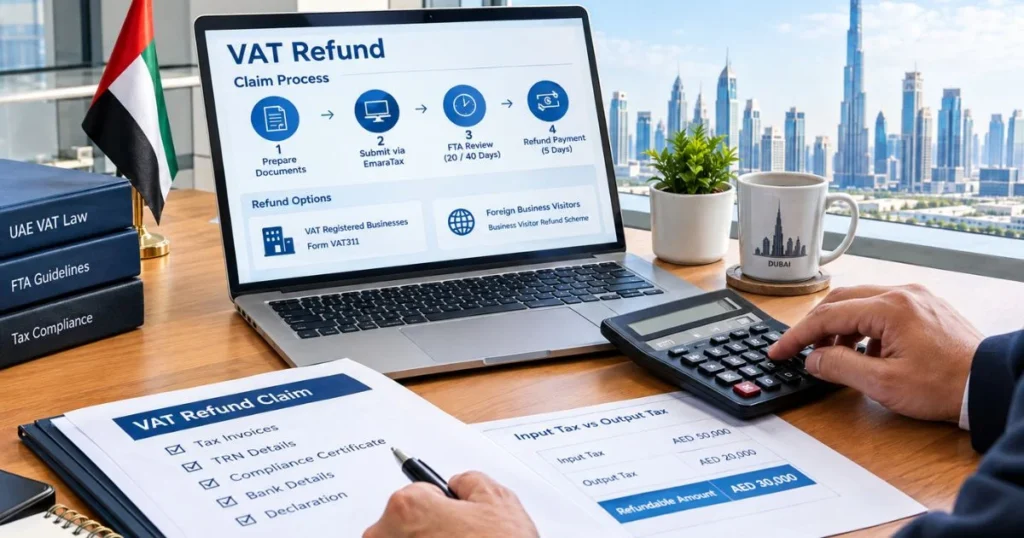
A UAE business claims a VAT refund when input tax exceeds output tax for a tax period. The FTA returns this excess through Form VAT311 for registered businesses, or the Business Visitor Refund Scheme for foreign companies.
What a VAT Refund Means for a UAE Business
A VAT refund happens when a business pays more input tax than it collects in output tax. The Federal Tax Authority tracks this gap on every VAT return. Each tax period ends with two outcomes. The business owes money, or the FTA owes the business money.
This gap creates a net VAT position. A positive gap is VAT payable. A negative gap is VAT refundable, also called an excess recoverable tax or credit balance. This differs from reimbursement, which recovers a client’s cost, not FTA tax.
The Two VAT Refund Paths in the UAE
VAT Registered UAE Businesses and Form VAT311
A VAT registered business claims a refund through Form VAT311. The business needs an active TRN. It logs into the EmaraTax portal and opens the Special Refunds section. This refund request form covers excess input VAT for a domestic taxpayer.
Foreign Business Visitors Without a UAE Establishment
The Business Visitor Refund Scheme covers a foreign business with no place of establishment in the UAE. This unregistered business submits a Tax Compliance Certificate with UAE Embassy attestation. A reciprocity condition applies unless the applicant is a GCC state or non implementing state.
Which Path Applies to Your Business
The UAE establishment test decides your path. A TRN holder with taxable person status uses VAT311. A non resident business uses the visitor scheme. Run the refund eligibility test before the annual submission window closes each calendar year claim period.
What You Can Actually Reclaim
Recoverable Business Expenses
A business reclaims VAT on office rent, utilities, and professional services. Equipment purchase and import VAT also qualify. So does staff catering under general business overhead. Each claim needs a valid tax invoice requirement and a clear taxable supply link.
Blocked and Non Recoverable Expenses
The FTA blocks VAT on entertainment services and client hospitality. This non employee entertainment rule creates blocked input tax. A personal use motor vehicle counts as an employee related expense. VAT tied to an exempt supply cost stays non recoverable too.
Mixed Use and Apportionment Rules
Apportionment splits VAT across mixed supplies. A business separates taxable and exempt supplies to find its general overhead VAT share. The Capital Asset Scheme applies above a capital asset value threshold. It runs through an annual adjustment period, including any building use adjustment.
Eligibility Conditions for Each Refund Scheme
Conditions for VAT Registered Businesses
A business needs VAT registered status and an active TRN. Every claim requires an FTA compliant tax invoice with a clear taxable supplies link. The timely reclaim period follows the following tax period rule if the business misses its first window.
Conditions for Foreign Business Visitors
A foreign visitor submits a Tax Compliance Certificate, often called a business status certificate, from its competent tax administration. The claim needs authorised signatory proof and a passport of the authorised signatory. The applicant’s home must be a reciprocal refund country within the twelve calendar month claim period.
How the Refund Process Works Through the FTA
Filing Form VAT311 Through EmaraTax
The process starts with VAT return submission. The business makes the box 15 refund election on the excess recoverable tax field. It opens the VAT Refunds navigation and completes the refund request form with TRN and legal entity details and an authorised signatory declaration.
Required Tax Invoices and Compliance Certificates
Every claim needs a valid tax invoice showing the supplier TRN, invoice date, and VAT amount in AED. Foreign claimants attach a Tax Compliance Certificate. Both paths need proof of payment, usually a bank validation letter.
Review Timelines and FTA Processing Windows
The FTA works within a 20 business day review window. Foreign visitor claims run on a 40 working day processing period. Once approved, the refund payment timeline moves fast. A five business day payout follows the FTA verification stage, unless an additional documentation request delays it.
Common Reasons the FTA Rejects or Delays a Refund Claim
Non Compliant Tax Invoices
A missing supplier TRN or incorrect VAT amount causes a non compliant invoice. Simplified tax invoice misuse creates the same problem. Any of these turns the claim into an invalid claim the FTA won’t process.
Unresolved Penalties Reducing the Refundable Balance
A late registration penalty cuts into a refund fast. This administrative penalty can reach AED 20,000. An unpaid penalty deduction applies before payout. The FTA favors a business with penalty free account status.
Mismatches Between VAT Returns and the Refund Form
The FTA compares VAT return figures against VAT311 figures. Any accounting record mismatch triggers a query. Reconciliation fixes small gaps. Larger errors need a voluntary disclosure before the claim moves forward.
Free Zone Considerations for VAT Refunds in the UAE
Free Zone VAT Treatment and Designated Zones
A free zone gets designated zone status from the FTA. DMCC, JAFZA, DIFC, RAKEZ, and ADGM all hold this status. Transfers between designated zones allow VAT free movement within a designated zone under set conditions.
How Free Zone Entity Structure Affects Refund Claims
A free zone trading model often runs on export heavy revenue. This creates zero rated output VAT against standard rated input cost. The gap builds a structural refund position. Any claim still needs the free zone audit requirement filed through the approved auditor list.
Working With a Registered Tax Agent on Your Refund Claim
What an FTA Approved Tax Agent Does During a Refund Claim
A tax agent handles refund claim preparation from start to finish. This includes a full documentation review and FTA correspondence handling. If a claim gets challenged, the agent manages objection submission and audit representation. Every invoice passes an invoice compliance check first.
When to Bring In Representation Before Filing
A pre-filing review catches errors early. This matters most for a high value refund claim or a recurring refund request. A complex documentation case raises FTA audit risk without one.
FAQs
Can a New Business Claim a VAT Refund?
A new VAT registration can recover pre-registration input VAT on its first VAT return. This covers goods held in inventory and services under a five year prior service claim.
How Long Does a VAT Refund Take in the UAE?
The FTA works within a 20 business day decision window. Approved claims move to a five business day payment. Some cases show processing time variance if documents are incomplete.
Can Excess Input VAT Be Carried Forward Instead of Refunded?
A business makes a carry forward election instead of requesting cash. This creates a future VAT liability offset through the box 15 choice, building a subsequent tax period credit.
What Happens If Part of a Refund Claim Is Rejected?
A partial rejection splits the claim in two. The disallowed amount stays unpaid, while the approved amount payout proceeds. Fix the gap through correction in future return or a reconsideration process.
Do Free Zone Companies Follow the Same Refund Process as Mainland Businesses?
Free zone companies follow the same VAT311 process as mainland businesses. The designated zone distinction adds a free zone documentation standard beyond the standard mainland comparison.
Talk to an FTA Registered Tax Agent About Your VAT Refund
An FTA Tax Agent under TAAN 20065132 handles your claim from start to finish. The Assurance Corps VAT Refunds service covers documentation, filing, and FTA correspondence. Submit a consultation request today for direct refund filing support.