Small Business Relief gives eligible UAE businesses a 0% corporate tax rate. It sits under UAE Corporate Tax law. The relief now runs through 31 December 2029, extended from 2026. This article explains exactly who qualifies. It covers who’s excluded, and what a business gives up by electing it.
What Small Business Relief Actually Means Under UAE Corporate Tax
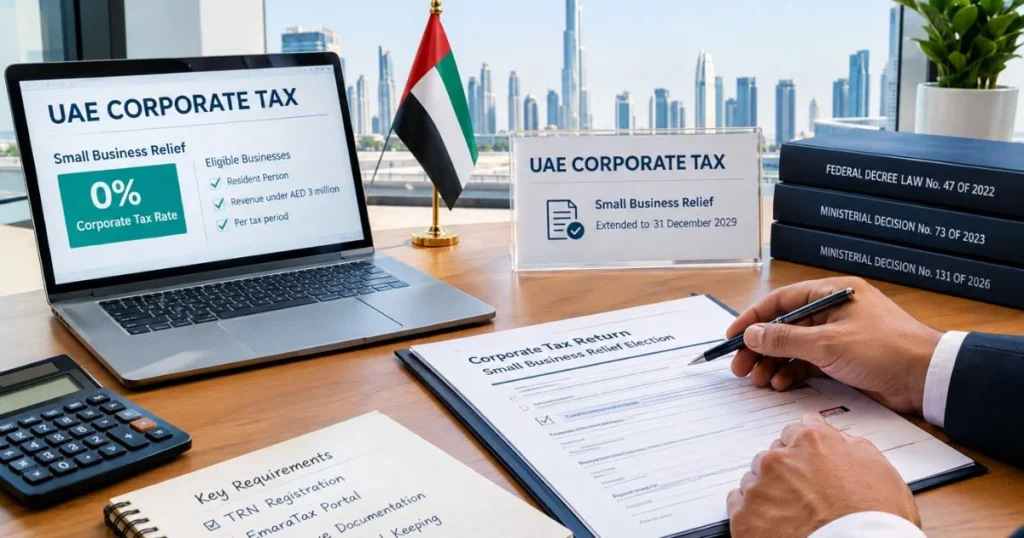
Small Business Relief gives eligible UAE businesses a 0% corporate tax rate. Set under Article 21 of Federal Decree Law No. 47 of 2022, a Resident Person, natural or juridical, can be deemed to have no taxable income for a tax period.
Corporate Tax Law confirms this through Ministerial Decision No. 73 of 2023. The corporate tax election allows cash basis accounting and brings simplified compliance with the Federal Tax Authority.
Small Business Relief Now Runs Through 2029, Not 2026
Small Business Relief now runs until 31 December 2029, not 31 December 2026. The UAE Ministry of Finance issued Ministerial Decision No. 131 of 2026, this extension announcement covers tax periods commencing on or after 1 June 2023. The AED 3 million threshold stays unchanged.
This legal basis amendment updates the law, but the Federal Tax Authority guidance page on tax.gov.ae still shows the old date. Businesses should check the corporate tax topics page directly for confirmation.
Who Qualifies for Small Business Relief
A Resident Person qualifies if gross revenue stays under AED 3 million in the current tax period. This counts revenue, not profit. The look back rule checks all previous tax periods too. This applies to a UAE incorporated company and any natural person carrying on business.
Revenue follows accounting standards applied in UAE, including IFRS and IFRS for SMEs. Businesses need a Tax Registration Number through the EmaraTax portal. Keep revenue documentation ready, since election for each tax period requires fresh confirmation. The UAE Tax Deadlines Calendar can help businesses track relevant tax deadlines and maintain timely compliance.
Who Is Excluded from Small Business Relief
A Qualifying Free Zone Person, or QFZP, cannot claim this relief. This entity already gets a 0% qualifying income rate under separate rules. A multinational enterprise group, or MNE group, is excluded too, if consolidated group revenue exceeds AED 3.15 billion. These groups file a Country by Country Report instead.
A Non Resident Taxable Person also does not qualify. Anti abuse rules block artificial separation of business to dodge the threshold. General anti abuse provisions, transfer pricing, the arm’s length principle, and non qualifying income de minimis rules still apply.
What a Business Gives Up by Electing Small Business Relief
Loss carry forward and interest deduction limitation rules
A business loses the right to carry forward tax losses once it elects this relief. It cannot offset future taxable income with past losses. General interest deduction limitation rules also stop applying, along with net interest expenditure tracking. This creates disallowed interest treatment instead. Businesses near the threshold should treat this as a strategic tax planning decision, since the relief brings deemed zero taxable income.
Tax grouping and other corporate tax reliefs
A tax group cannot consolidate taxable income and losses while claiming this relief. Corporate tax group eligibility stops during the election period. Businesses also lose other reliefs, including investment asset relief and exempt income provisions. This reflects the mutual exclusivity of reliefs built into the law.
Record keeping still required for seven years
Electing this relief does not remove record keeping duties. Businesses must keep invoices, receipts, order records, and bank statements for a full seven year retention period, in digital record format. These financial records substantiating revenue matter directly during a Federal Tax Authority audit or FTA query.
How to Elect Small Business Relief in Your Corporate Tax Return
Registering for Corporate Tax and obtaining a Tax Registration Number
Every eligible business needs a Tax Registration Number, or TRN, before filing. Corporate tax registration happens through the EmaraTax portal, using a UAEPass login. This is mandatory registration, with a fixed registration deadline. Missing it brings a late registration penalty, so businesses should register early.
Making the election inside the EmaraTax return
The election happens inside the EmaraTax return itself, using the election checkbox on the Corporate Tax Return Form. This is a per tax period election, with no retroactive election allowed. Filing without electing means standard tax rules applied instead, at the normal rate.
FAQs
Does Small Business Relief apply automatically?
Small Business Relief has no automatic application. It requires an active election requirement inside the filed return on EmaraTax. Skipping this step brings a missed election consequence standard tax rates apply instead.
What happens if my revenue exceeds AED 3 million in one year?
A threshold breach causes permanent loss of eligibility for that period. The standard 9% corporate tax regime applies instead. If revenue falls back below threshold later, re-election in future periods becomes possible again.
Can a Free Zone company still claim Small Business Relief?
A Free Zone company can claim it only if Qualifying Free Zone Person status is not elected. Mutual exclusivity blocks combining this with the 0% qualifying income regime a qualified tax professional review confirms eligibility.
What is the difference between Small Business Relief and the AED 375,000 tax free band?
The AED 375,000 threshold sets the standard regime 0% band, taxing income above it at the 9% rate above threshold. This is a taxable income basis vs revenue basis separate mechanisms entirely.
Get Expert Help with Small Business Relief
Assurance Corps is an FTA registered Tax Agent with a valid Tax Agency Number. As an FTA Certified Tax Agency, we offer corporate tax filing services in Dubai UAE. Businesses unsure about eligibility can start with a consultation booking for direct eligibility confirmation.