A UAE business with two or more related companies can form a Corporate Tax Group under Article 40 of the Corporate Tax Law. This works well when entities share 95% common ownership and run frequent intra group transactions. Grouping cuts filing down to one consolidated tax return. But it isn’t right for every business. Grouping removes each entity’s AED 375,000 exemption and adds joint and several liability for group debt. This article breaks down the eligibility conditions, benefits, drawbacks, and the exact FTA application steps.
What Is a Corporate Tax Group Under UAE Corporate Tax Law
Legal Definition Under Article 40 of the Corporate Tax Law
Article 40 of the UAE Corporate Tax Law lets two or more Taxable Persons act as one single Taxable Person. This rule sits inside Federal Decree Law No. 47 of 2022. It applies from the tax period commencing 1 June 2023. Only resident persons and juridical persons can use it. The Ministry of Finance set this rule to simplify taxable income reporting for related UAE companies.
Parent Company and Subsidiary Roles in a Tax Group
The parent company leads the group as its representative member. Each subsidiary joins under the parent’s control. The parent handles all tax administration responsibility for the group. It gets one group Tax Identification Number (TIN) from the FTA. The parent also files a single tax return, called a consolidated tax return, and manages every FTA correspondence and tax compliance obligation.
Eligibility Conditions to Form a UAE Corporate Tax Group
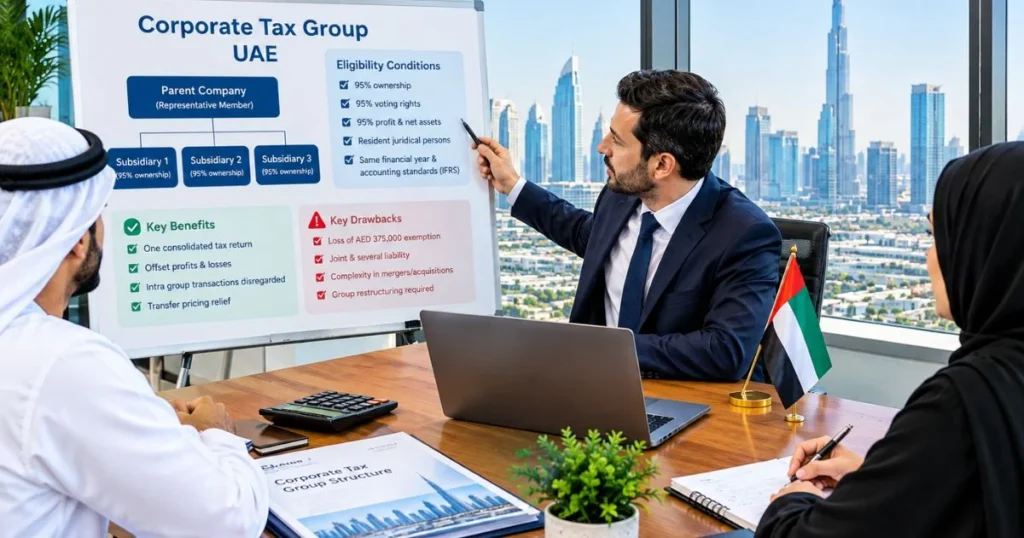
A UAE Corporate Tax Group needs a strict common ownership structure. The parent must hold a 95% shareholding threshold, 95% voting rights, and 95% profit and net assets entitlement. This can be direct ownership or indirect ownership. Only resident juridical persons qualify as a UAE tax resident person. Natural persons and unincorporated joint ventures are excluded.
Every member must share the same financial year and follow the same accounting standards, usually IFRS. An exempt person cannot join. Neither can a Qualifying Free Zone Person (QFZP). A Permanent Establishment or a branch of foreign company stays excluded too.
Tax Group vs Qualifying Group: Knowing the Difference
A Qualifying Group works under relaxed grouping conditions compared to a full Tax Group. It only needs a 75% ownership threshold, met through common holding, cross holding, or third party 75% common ownership. Members keep separate CT registration and file separate tax returns for Qualifying Group members.
The main benefit is easier transfer of assets and liabilities. Companies move assets at net book value asset transfer, avoiding extra tax cost. A Qualifying Group also allows the transfer of tax losses between eligible entities without full consolidation.
Benefits of Forming a Corporate Tax Group
One Consolidated Return Instead of Separate Filings
A Corporate Tax Group files one consolidated tax return instead of many. The parent company files on behalf of group members. This gives a single CT registration number for everyone. Filing happens through single tax return filing, not separate ones. The group gets a nine month filing window for its annual CT return. This means reduced filing volume and separate registration and filing avoided.
Offsetting Profits and Losses Across Group Members
Group members can use offsetting profits and losses together. A loss making entity can offset a profitable entity’s income. This creates tax loss transfer across the group. The FTA calculates one aggregated taxable profit or aggregated taxable loss. This lowers the group taxable income calculation overall. Businesses gain a real cash flow benefit from this setup.
Disregarded Intra Group Transactions and Transfer Pricing Relief
Inside a Tax Group, intra group transactions are disregarded for tax purposes. Members get an arm’s length principle exemption on internal deals. This means transfer pricing requirements waived for related party transactions. Companies can complete an asset and liability transfer freely. There’s no transfer pricing documentation burden to manage. Businesses also avoid fair market value proof for each transfer.
Drawbacks and Risks of Forming a Corporate Tax Group
How Tax Grouping Affects the AED 375,000 Corporate Tax Threshold
UAE Corporate Tax applies a 0% rate to taxable income up to AED 375,000, subject to the applicable rules. Joining a Tax Group changes this rule. The individual exemption limit lost applies once grouping starts. The FTA applies a group wide threshold application instead. This raises the group’s total taxable income threshold exposure. Businesses face a small business relief exclusion post grouping as a direct result.
Joint and Several Liability Among Group Members
A Tax Group carries joint and several liability for all members. The Corporate Tax Payable by the Tax Group becomes a shared debt. This creates real parent company liability for every subsidiary’s tax. It also creates subsidiary liability for the parent’s tax. The FTA allows FTA recovery from any member at any time. This makes tax debt a full collective tax obligation.
Complications During Mergers, Acquisitions, or Exit
Group changes create real filing problems for businesses. An entity leaving the tax group needs fresh registration. An entity joining the tax group faces its own review. Any shareholding change can break eligibility instantly. This matters most during mergers and acquisitions impact situations. Exits also force a tax period adjustment on exit. All of this adds real group restructuring work.
How to Apply to Form a Tax Group With the FTA
Documents the Parent Company and Subsidiaries Must Prepare
The parent and subsidiaries need clean financial statements of parent and subsidiaries. They also need an organisational chart with ownership percentages. Every member must sign the Tax Group Agreement. Each entity needs its own Corporate Tax registration. Businesses must show proof of 95% ownership. An accounting standard confirmation also stays required.
Submitting the Application and Receiving the Group Tax Identification Number
The group applies through FTA online portal submission. The FTA reviews and grants a Tax Identification Number. This TIN issuance confirms the group formally. Businesses then get a group registration confirmation. The tax period start date gets determined by FTA. The parent keeps full compliance responsibility going forward.
Should You Form a Corporate Tax Group? A Decision Framework
When Grouping Makes Sense for Multi-Entity UAE Businesses
Grouping fits multiple UAE entities under common ownership well. It suits businesses with frequent intra group transactions between companies. A family business with multiple entities often benefits here. So does a developer with property and facilities management subsidiaries. These structures usually have a real simplified compliance need.
When to Keep Entities Filing Separately Instead
Some businesses gain more by staying separate instead. Preserving individual AED 375,000 exemption matters for smaller entities. Others focus on avoiding joint and several liability risks. This fits entities not meeting 95% threshold requirements. It also suits companies with differing financial year ends or standalone Small Business Relief eligibility.
FAQs
Can a Free Zone Company Join a Corporate Tax Group?
No. A Qualifying Free Zone Person cannot join a Tax Group. This free zone exclusion from Tax Group protects its 0% Corporate Tax rate on Qualifying Income. A non qualifying free zone person still stays excluded too.
What Happens If a Subsidiary Leaves the Tax Group Mid Year?
Leaving triggers a tax period adjustment immediately. The subsidiary faces deregistration from group status and needs standalone Corporate Tax registration. The parent must file an FTA notification obligation for this group composition change.
Does VAT Grouping Follow the Same Rules as Corporate Tax Grouping?
No. VAT grouping conditions differ from Corporate Tax grouping conditions. A VAT Group gets one VAT Tax Registration Number, treating members as a single taxable person for VAT, under different grouping rules for VAT and CT.
Can a Business Choose a Qualifying Group Instead of a Full Tax Group?
Yes. A Qualifying Group needs only a 75% ownership threshold. Members keep separate registration retained while using net book value transfer. This gives relief without full consolidation for eligible businesses.
Does Forming a Tax Group Affect Eligibility for Small Business Relief?
Yes. Small Business Relief eligibility changes under grouping. The AED 375,000 threshold faces group wide application of threshold, causing individual entity relief lost. Groups must still meet the revenue threshold AED 3 million limit.
Need Help Deciding? Talk to a Dubai Based Corporate Tax Advisor
Assurance Corps works as an FTA Certified Tax Agency in the UAE. As an FTA registered Tax Agent, holding a valid TAAN, it offers full corporate tax group registration service. This Dubai based advisory also handles corporate tax filing on behalf of client businesses across the UAE.